An Alabama Mineral Buyer Built Around the Recorded Interest

An Alabama Mineral Buyer Built Around the Recorded Interest
County, legal description, acreage, reservation language, estate type, formation and depth limits, and ownership fraction establish the Alabama interest under review.
Every later instrument is read against that description before any number is discussed.
County, legal description, acreage, reservation language, estate type, formation and depth limits, and ownership fraction establish the Alabama interest under review.
Every later instrument is read against that description before any number is discussed.

County, legal description, acreage, reservation language, estate type, formation and depth limits, and ownership fraction establish the Alabama interest under review.
Every later instrument is read against that description before any number is discussed.


Owner fraction, lease royalty, unit allocation, division order, payor record, deductions, and adjustment history should explain the decimal and net amount on the statement.

Owner fraction, lease royalty, unit allocation, division order, payor record, deductions, and adjustment history should explain the decimal and net amount on the statement.

Producing Black Warrior cash flow, south Alabama oil income, undeveloped acreage, lease burdens, title risk, and future optionality belong on distinct evidence and assumption lines.
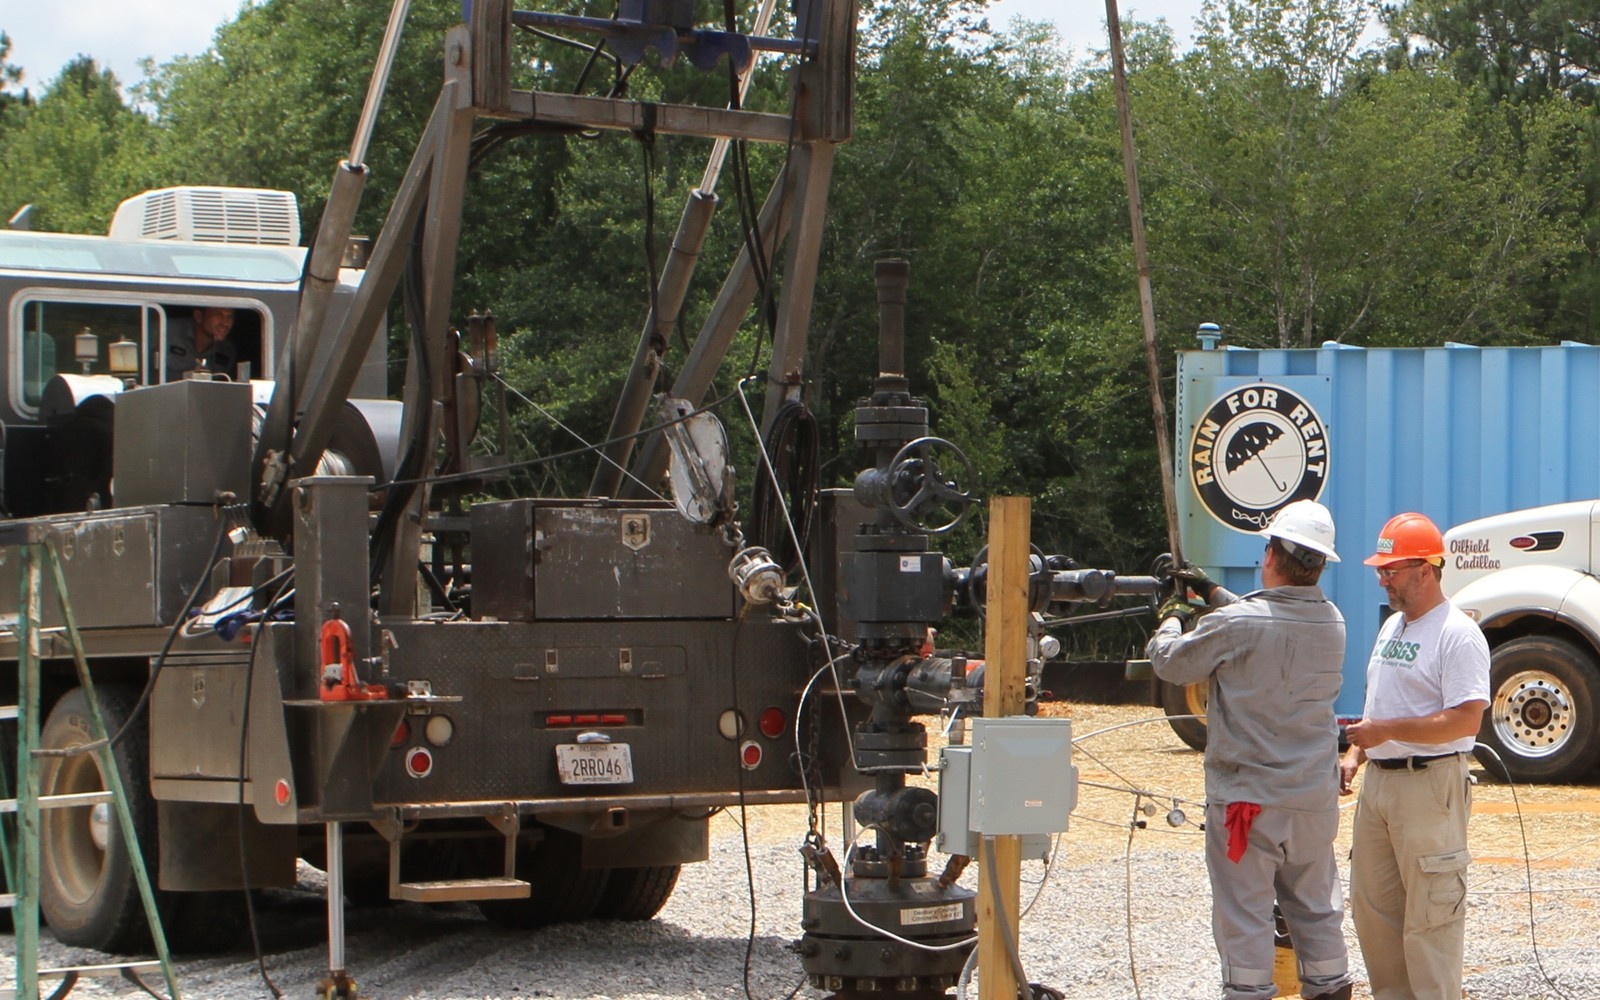
Producing Black Warrior cash flow, south Alabama oil income, undeveloped acreage, lease burdens, title risk, and future optionality belong on distinct evidence and assumption lines.
Producing Black Warrior cash flow, south Alabama oil income, undeveloped acreage, lease burdens, title risk, and future optionality belong on distinct evidence and assumption lines.


The agreement, mineral deed, retained-interest clause, settlement record, funding confirmation, and county recording should describe the same tract, estate, and ownership fraction.
If one document disagrees with the others, the difference is resolved before closing, not after.

The agreement, mineral deed, retained-interest clause, settlement record, funding confirmation, and county recording should describe the same tract, estate, and ownership fraction.
If one document disagrees with the others, the difference is resolved before closing, not after.
The agreement, mineral deed, retained-interest clause, settlement record, funding confirmation, and county recording should describe the same tract, estate, and ownership fraction.
If one document disagrees with the others, the difference is resolved before closing, not after.

